 Gemini
Global Real Estate Outlook Q4 2026 - GRI Institute Report
Examining cross-border capital flows, core trends, strategic opportunities, and structural challenges in real estate across APAC, EMEA, and the Americas
September 17, 2026Real Estate
Written by:Rory Hickman
Executive Summary
Global commercial real estate enters late 2026 amidst steady macroeconomic expansion and a broad rebound in institutional confidence, despite ongoing geopolitical friction and delayed monetary easing amid divergent policies.
Cross-border capital flows and transaction volumes are recovering across major gateway nodes as pricing clarity emerges, yet the overarching market remains defined by a severe structural bifurcation.
As occupiers and investors prioritise flight-to-quality and sustainability, equity is aggressively concentrating in prime, energy-efficient assets, digital infrastructure, resilient logistics networks, and purpose-built living formats.
Combining the collected senior decision-maker insights from GRI Institute events, the latest market news, and recent industry reports from CBRE, Colliers, Cushman & Wakefield, JLL, Knight Frank, Savills, and other leading sources, this report explores the trends, opportunities, and challenges shaping real estate across APAC, Europe, GCC, Latin America, and the US.
Ahead of the GRI Global Summit, this strategic report delivers essential market intelligence to help industry executives navigate structural shifts, optimise capital allocation, and mitigate emerging operational risks.
By providing a clear global perspective on market realities and growth vectors, these insights offer global allocators and investors the foresight needed to execute high-conviction strategies, drive long-term value, and build the future of real estate.
► Join the industry’s top leaders at the GRI Global Summit in Abu Dhabi on 9th December
Cross-border capital flows and transaction volumes are recovering across major gateway nodes as pricing clarity emerges, yet the overarching market remains defined by a severe structural bifurcation.
As occupiers and investors prioritise flight-to-quality and sustainability, equity is aggressively concentrating in prime, energy-efficient assets, digital infrastructure, resilient logistics networks, and purpose-built living formats.
Combining the collected senior decision-maker insights from GRI Institute events, the latest market news, and recent industry reports from CBRE, Colliers, Cushman & Wakefield, JLL, Knight Frank, Savills, and other leading sources, this report explores the trends, opportunities, and challenges shaping real estate across APAC, Europe, GCC, Latin America, and the US.
Ahead of the GRI Global Summit, this strategic report delivers essential market intelligence to help industry executives navigate structural shifts, optimise capital allocation, and mitigate emerging operational risks.
By providing a clear global perspective on market realities and growth vectors, these insights offer global allocators and investors the foresight needed to execute high-conviction strategies, drive long-term value, and build the future of real estate.
► Join the industry’s top leaders at the GRI Global Summit in Abu Dhabi on 9th December
Key Takeaways
- Global institutional confidence and cross-border commercial real estate flows are rebounding significantly, supported by steady macroeconomic momentum despite geopolitical supply-chain friction and delayed monetary easing.
- Commercial real estate is undergoing a severe structural bifurcation, where capital and tenants heavily concentrate in premium, energy-efficient assets while secondary commodity space faces rising vacancy and obsolescence.
- Institutional capital allocation is pivoting towards resilient, demand-driven sectors, particularly digital infrastructure, nearshoring logistics networks, and purpose-built living formats designed to address chronic housing shortages.
Global Overview
► Macroeconomic and Geopolitical Outlook
Global real gross domestic product expansion is tracking at approximately 3.0% in 2026, underpinned by steady economic momentum across both advanced and emerging economies.Mid-2026 geopolitical tensions in the Middle East and transit disruptions through the Strait of Hormuz chokepoint have created short-term maritime supply-chain friction, energy benchmark volatility, and freight rate spikes.
Within the GCC region, GDP-weighted CPI inflation is forecast to rise to 2.5% in 2026 before easing to 1.8% in 2027, with price controls and food-import insurance keeping inflation manageable despite cargo import volumes remaining below pre-conflict levels.
Dollar-pegged exchange rate regimes across GCC countries have delayed widespread monetary easing until 2027, keeping central bank policy rates tightly anchored to the US Federal Reserve.
Simultaneously, input-cost inflation and supply-chain friction have supercharged corporate efficiency imperatives, raising local-currency interior fit-out outlays by 10% in London and Seoul, and 8% in New York.
Corporate occupiers are aggressively consolidating redundant operational footprints, densifying core corporate headquarters, and demanding verified environmental sustainability from landlords to suppress building running costs.
Consequently, occupiers are demonstrating a strong willingness to pay record rental rates for premium, energy-efficient space while systematically rejecting secondary commodity buildings.
Strategic trade frameworks continue to evolve despite regional headwinds. The India-Middle East-Europe Economic Corridor (IMEC) is expanding as a strategic multimodal network of trade, energy, and digital routes connecting India, the UAE, Saudi Arabia, and Europe, reinforcing regional logistics integration.
In tandem, the India-UAE economic partnership is deepening through BRICS expansion, targeting bilateral trade of USD 200 billion by 2032 driven by advanced technology, digital economy investments, and integrated logistics corridors.
National strategic initiatives, such as the UAE's National Investment Strategy (NIS) 2031, the National Investment Fund with an initial capitalisation of approximately USD 10 billion, and the AED 1 billion National Industrial Resilience Fund, are accelerating local manufacturing, supply-chain resilience, and global capital attraction.
► Real Estate and Investment Scene
Global commercial real estate enters late 2026 governed by structural operational bifurcation, where capital availability, pricing discovery, and operational performance have decoupled across property sectors, asset tiers, and geographic borders.Direct global commercial real estate investment volume expanded 28% year-on-year in Q2 2026 to USD 237 billion, bringing H1 2026 total investment to USD 466 billion.
Institutional confidence has rebounded significantly, with 87% of surveyed global institutions, representing USD 1.4 trillion in assets under management according to Cushman & Wakefield, planning to maintain or increase direct real estate allocations through late 2026.
Underwriting parameters have undergone a structural reset around higher exit capitalisation rates, pricing core multifamily exits at 4.75%-5.25% and core logistics between 4.75%-5.5%.
Direct global living sector investment is projected by JLL to absorb as much as USD 1,400 billion over the next five years, driven by chronic urban housing shortages across major gateway cities.
Digital infrastructure has solidified as an essential real asset class, with data centre pipelines reaching 26.5 GW in Asia-Pacific (APAC) and live colocation capacity hitting 3.8 GW in European FLAP-D markets (Frankfurt, London, Amsterdam, Paris, and Dublin), where overall vacancy compressed to 6.4%.
Underwriting for data centres and digital infrastructure is governed strictly by substation power availability, grid predictability, and utility interconnection queues rather than traditional geography.
Market liquidity continues to concentrate in highly transparent markets. Global real estate transparency continues to deepen, with the 13 "Highly Transparent" jurisdictions absorbing over 80% of direct cross-border capital and representing 56% of global income-producing real estate stock.
An extreme K-shaped operational split defines the commercial market, where prime Grade A trophy towers command historic rents and sub-5% vacancy due to return-to-office mandates and a multi-year freeze in speculative starts, while secondary commodity space faces severe vacancy, high tenant concession burdens, and unviable decarbonisation costs.
Commercial real estate credit markets remain highly active, with debt funds, CMBS, insurance companies, and banks competing for senior risk at SOFR/EURIBOR + 180 to 220 bps margins for living and logistics, compared to >350 bps for secondary commercial stock.
Private capital fundraising is concentrating heavily among top-tier managers, with funds exceeding USD 1 billion in size capturing 70% of total global fundraising, led by value-add (39%) and opportunistic (28%) strategies.
Furthermore, the democratisation of real estate investing through semi-liquid and evergreen fund vehicles, such as ELTIF 2.0, LTAF, and 401(k) private market inclusion, is projected to unlock over USD 800 billion of incremental private wealth allocations by 2030.
► Cross-border Deal Flow
Global cross-border commercial real estate flows rebounded 25% to 31% year-on-year through mid-to-late 2026, driven by institutional pricing clarity and credit market recovery.North American institutional investors remain the largest net exporters of real estate capital, deploying equity into European logistics, Central London office repositioning, purpose-built student accommodation (PBSA), Japanese logistics, Australian life sciences, and Indian Grade A office parks.
Sovereign wealth funds and family offices from the UAE, Saudi Arabia, and Qatar continue to selectively deploy capital into defensive US and Western European assets, targeting Central London commercial towers, core distribution hubs, and FLAP-D data centres.
Tracked GCC flow into US real estate has diverged from broader US transaction volume due to oil revenue lags, domestic real estate return competition, capital diversion to artificial intelligence (AI) infrastructure, and a structural transition away from pooled funds toward direct transactions, separately managed accounts (SMAs), and joint ventures (JVs).
Inbound capital into the GCC is anchored by record foreign real estate investment in Dubai, which reached AED 148 billion in Q1 2026, up 26% year-on-year, and Saudi Arabia's Regional Headquarters initiative, where over 780 firms in Riyadh pushed Grade A office occupancy to 98%.
The EMEA region captures over 57% of global cross-border private wealth flows and holds six of the world's top ten international destination markets, led by the UK capturing 16.1% of global international flows.
Outbound European capital from France, Sweden, and Norway is deploying equity into North American and peripheral European logistics and multifamily portfolios.
In intra-European flows, Central and Eastern Europe (CEE) transaction volume reached EUR 5.5 billion in H1 2026, up 20% year-on-year, led by Poland capturing EUR 3.06 billion, a 72% year-on-year increase driven by nearshoring manufacturing and supply-chain logistics assets.
In the APAC region, cross-border volume surged 87% year-on-year in Q1 2026 to USD 16.3 billion, representing approximately 40% of regional investment.
This momentum was anchored by robust institutional allocations into Australian PBSA, Japanese logistics, and Indian tech parks, while Singapore's domestic market posted a record USD 11.5 billion in total Q1 transaction volume.
Mainland Chinese capital into Hong Kong commercial real estate rose 41% year-on-year in Q1 and 129% year-on-year in Q2 2026, targeting retail, owner-occupier properties, and discounted Central office towers.
In the Americas, US to Mexico cross-border flows are heavily concentrated in USMCA nearshoring logistics, with US institutional capital partnering with Mexican FIBRAs to finance border distribution parks in Monterrey, Juárez, and Tijuana, where vacancy sits below 2%.
Latin American private wealth from Argentina, Chile, and Colombia continues to seek capital preservation in US Sunbelt residential assets, Montevideo luxury schemes, and Pacific trade logistics corridors, including the Chancay Megaport in Peru.
Across all regions, institutional allocators are structurally shifting outbound deployment away from blind-pool funds toward SMAs, direct transactions, and co-investment JVs to ensure asset-level control, fee transparency, and governance oversight.
Regional Analysis
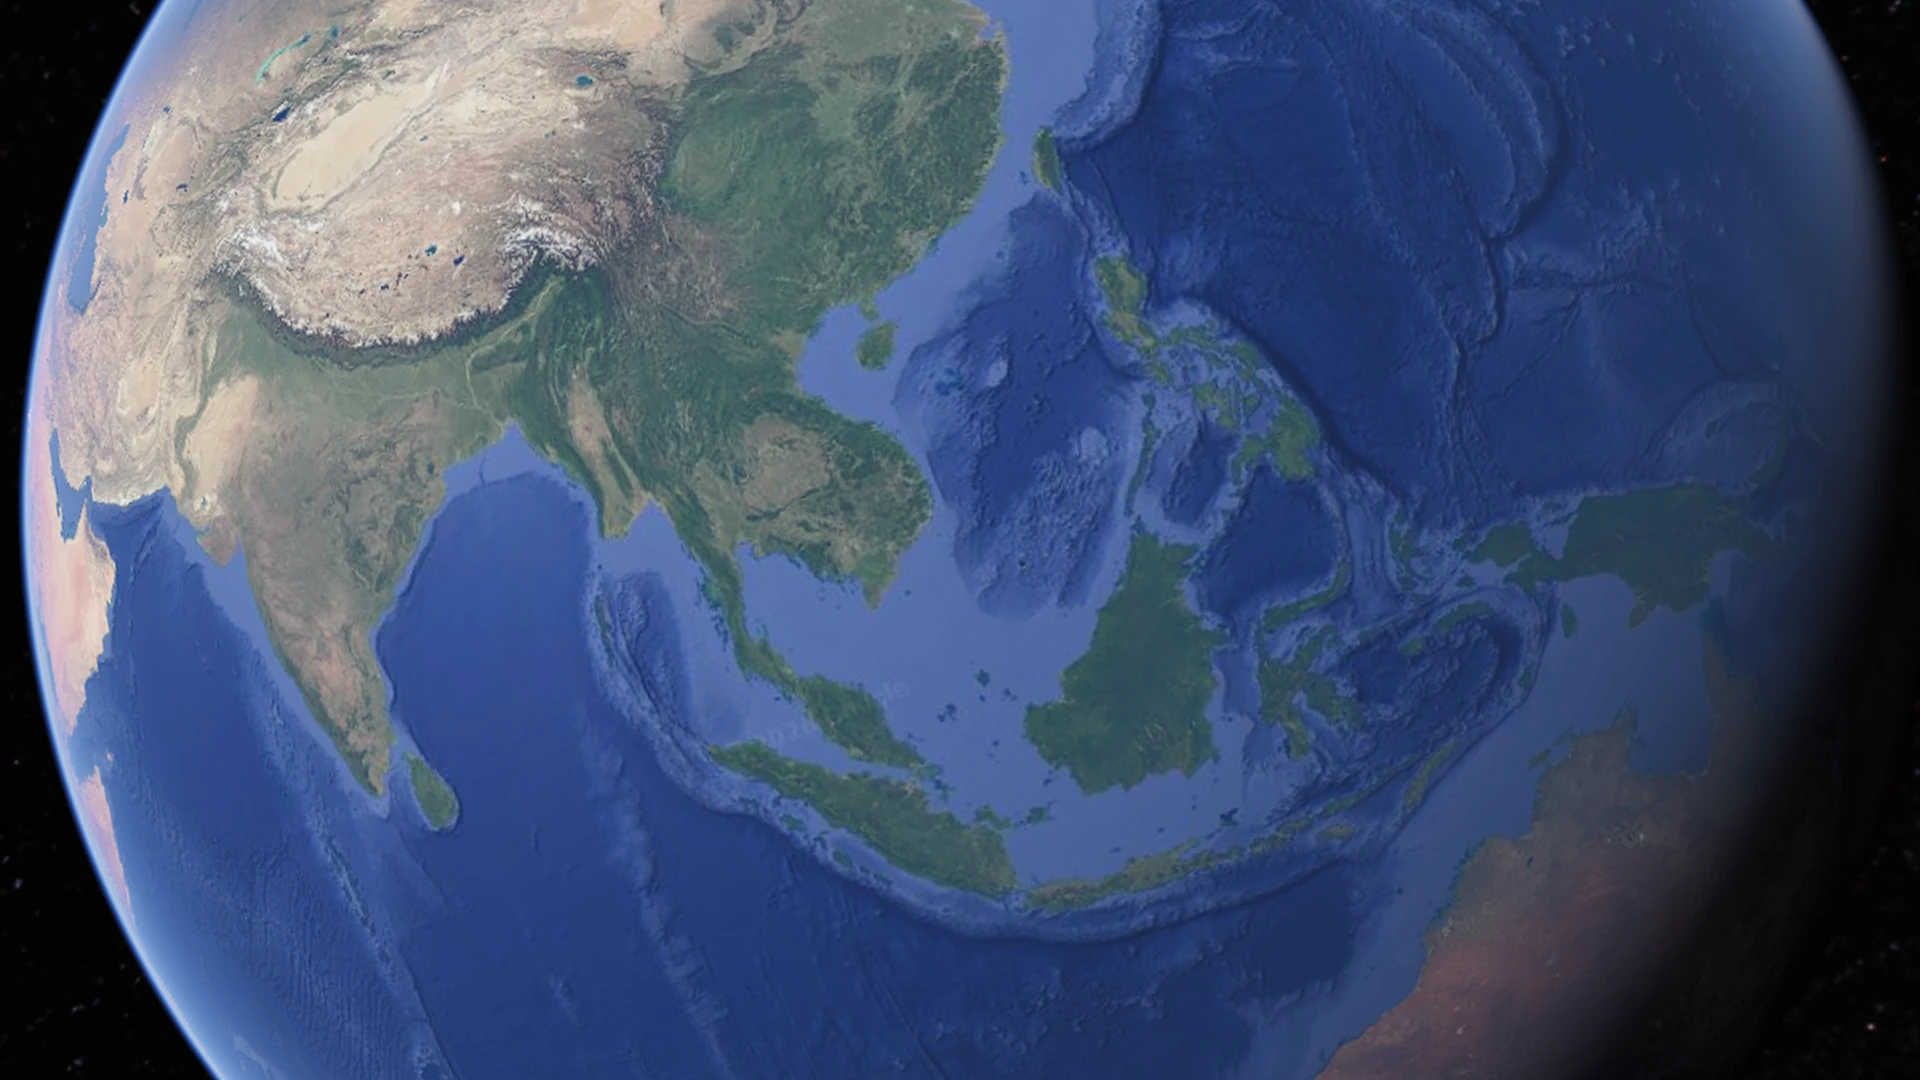
► Asia Pacific (APAC)
(Google Earth)
Current Trends
Regional investment volumes have rebounded strongly across Asia Pacific, driven by returning cross-border capital concentrating in deep, liquid gateway nodes.
Total returns are increasingly anchored by rental growth rather than capitalisation rate compression, as central banks across the region pause rate cuts or shift towards a hawkish monetary stance.
Simultaneously, robust demand for AI infrastructure and semiconductors continues to bolster broader economic expansion, driving strong occupier space requirements across tech-oriented hubs.
Opportunities
Investment opportunities are increasingly focused on hyperscale data centres and digital infrastructure, alongside prime office assets located in supply-constrained gateway cities.
Modern, automation-ready logistics facilities continue to attract institutional equity, while event-driven hospitality assets present attractive upside potential across major metropolitan centres.
Challenges
The region faces headwinds from hawkish policy shifts and central bank interest rate hikes in select markets, coupled with persistent geopolitical and trade friction. Furthermore, elevated construction costs continue to deter ground-up developments, while a widening performance split emerges between prime Grade A assets and secondary commodity stock.
▷ India
Current TrendsIndian real estate is experiencing record-breaking office leasing activity, propelled by multinational Global Capability Centres, domestic technology enterprises, and expanding financial groups.
Deep domestic capital reserves remain highly active alongside returning foreign institutional conviction, underpinned by rapid improvements in regulatory transparency and market maturity.
Opportunities
Key investment themes include modern Grade A logistics and industrial corridors across emerging regional clusters, hyperscale data centre campuses, and prime office parks. Additionally, newly enabled Small and Medium REIT structures are creating fresh avenues for capital deployment and liquidity.
Challenges
Development and expansion activity remain constrained by high land acquisition costs in primary metropolitan locations, severe land parcel fragmentation, and multi-layered regulatory approval processes. Localised infrastructure gaps also continue to present operational friction in secondary submarkets.
► India GRI 2026 is almost here - access the full agenda and see who's attending
▷ Australia
Current TrendsCommercial transaction activity in Australia is predominantly anchored by private capital deployment and resilient retail asset investment, while commercial completions face a severe slowdown due to high financing and construction outlays.
Sydney central business district (CBD) office net effective rents are demonstrating strong upward growth, supported by structurally tight logistics vacancy rates across major capital cities.
Opportunities
Institutional investors are targeting prime CBD office towers that stand to benefit from an acute multi-year supply freeze, alongside non-discretionary neighbourhood retail centres. Strategic allocations continue to flow into PBSA and build-to-rent (BTR) living formats designed to address structural housing shortfalls.
Challenges
Interest rate hikes by the Reserve Bank of Australia have driven yield decompression across secondary asset classes. Institutional sentiment is further impacted by new policy and tax restrictions targeting property investors, elevated construction tender costs, and localised supply-side logistics pressures.
▷ China
Current TrendsCommercial real estate transaction activity in China has accelerated sharply, driven primarily by domestic institutional funds and state-backed entities acquiring discounted assets. Office leasing markets remain firmly tenant-favourable across Tier 1 metros, forcing landlords to offer generous concession packages and flexible terms to safeguard portfolio occupancy.
Opportunities
Capital deployment is finding traction in stabilised, income-producing logistics parks and prime shopping centres within Tier 1 cities. Value-add strategies are targeting office-to-hotel conversions, as well as advanced industrial and high-tech manufacturing facilities aligned with national policy priorities.
Challenges
The investment landscape is weighed down by macroeconomic headwinds stemming from residential developer debt restructuring. Laggard office rental growth under heavy supply pressure continues to undermine capital value growth, while logistics rental projections have been downgraded in supply-laden submarkets.
▷ Japan
Current TrendsTokyo firmly maintains its status as a premier global safe haven, characterised by ultra-low Grade A office vacancy and sustained double-digit rental growth. Exceptional domestic capital liquidity and highly competitive lending spreads continue to preserve positive yield spreads for institutional investors.
Opportunities
Prime target sectors include Central Tokyo Grade A office towers, high-street retail flagships in premier shopping districts such as Ginza and Omotesando, and Tokyo Bay logistics hubs. Regional urban multifamily assets and hospitality properties also offer attractive yield profiles.
Challenges
Calibrated interest rate increases by the Bank of Japan are inducing mild yield softening across select office segments. High construction outlays pose challenges for refurbishment and new developments, while minor fluctuations in Chinese inbound tourism introduce temporary volatility in retail and hotel performance.
▷ Singapore
Current TrendsSingapore has rebounded strongly as a preferred regional private wealth and corporate haven, driving robust direct investment volumes and yield compression across prime assets. Extremely tight Grade A office supply, coupled with long-term Master Plan urban regeneration initiatives, underpins sustained capital value resilience.
Opportunities
Core investment avenues are concentrated in prime CBD office redevelopments, advanced manufacturing logistics, life sciences research facilities, and MICE-focused (meetings, incentives, conferences, and exhibitions) hospitality assets.
Challenges
Elevated operating and occupancy expenses are placing operational stress on non-core retail and food-and-beverage tenants. Furthermore, constrained near-term prime asset availability limits the active transaction pipeline for deploying institutional capital.
▷ South Korea
Current TrendsSouth Korea is witnessing sustained capital deployment and tight office vacancy across key Seoul business hubs, notably the Gangnam Business District (GBD) and Pangyo, driven by tech conglomerates, AI ventures, and professional services firms.
Concurrently, the global popularity of the Korean Wave is driving a strong recovery in hotel revenue per available room (RevPAR) and international visitor arrivals.
Opportunities
Investor interest centres on core Seoul CBD and GBD office towers, lifestyle hotel repositioning schemes, and dry logistics conversion projects capable of delivering secure cash flows.
Challenges
The market faces monetary friction from central bank hawkishness and Bank of Korea rate adjustments, alongside softening logistics yields, particularly within the oversupplied cold storage sector. Commercial tenant fit-out costs have also experienced a 10% year-on-year inflation spike.
▷ Hong Kong
Current TrendsDirect commercial property investment in Hong Kong has surged year-on-year, propelled by returning mainland institutional capital, private family wealth, and insurance funds targeting core re-priced assets. Central office vacancy is beginning to compress as corporate occupiers capitalise on lower rental baselines to secure prime space.
Opportunities
Attractive entry points are emerging in re-priced prime Central office space, high-street retail flagships, and luxury residential leasing. Value-add strategies are actively pursuing hotel-to-student accommodation conversions to meet strong student housing demand.
Challenges
Capital value appreciation remains sluggish, contributing to yield expansion across non-prime assets. Non-core retail rental softness and elevated operational overheads continue to weigh on broader market sentiment.
► Find all upcoming GRI Institute events in APAC here
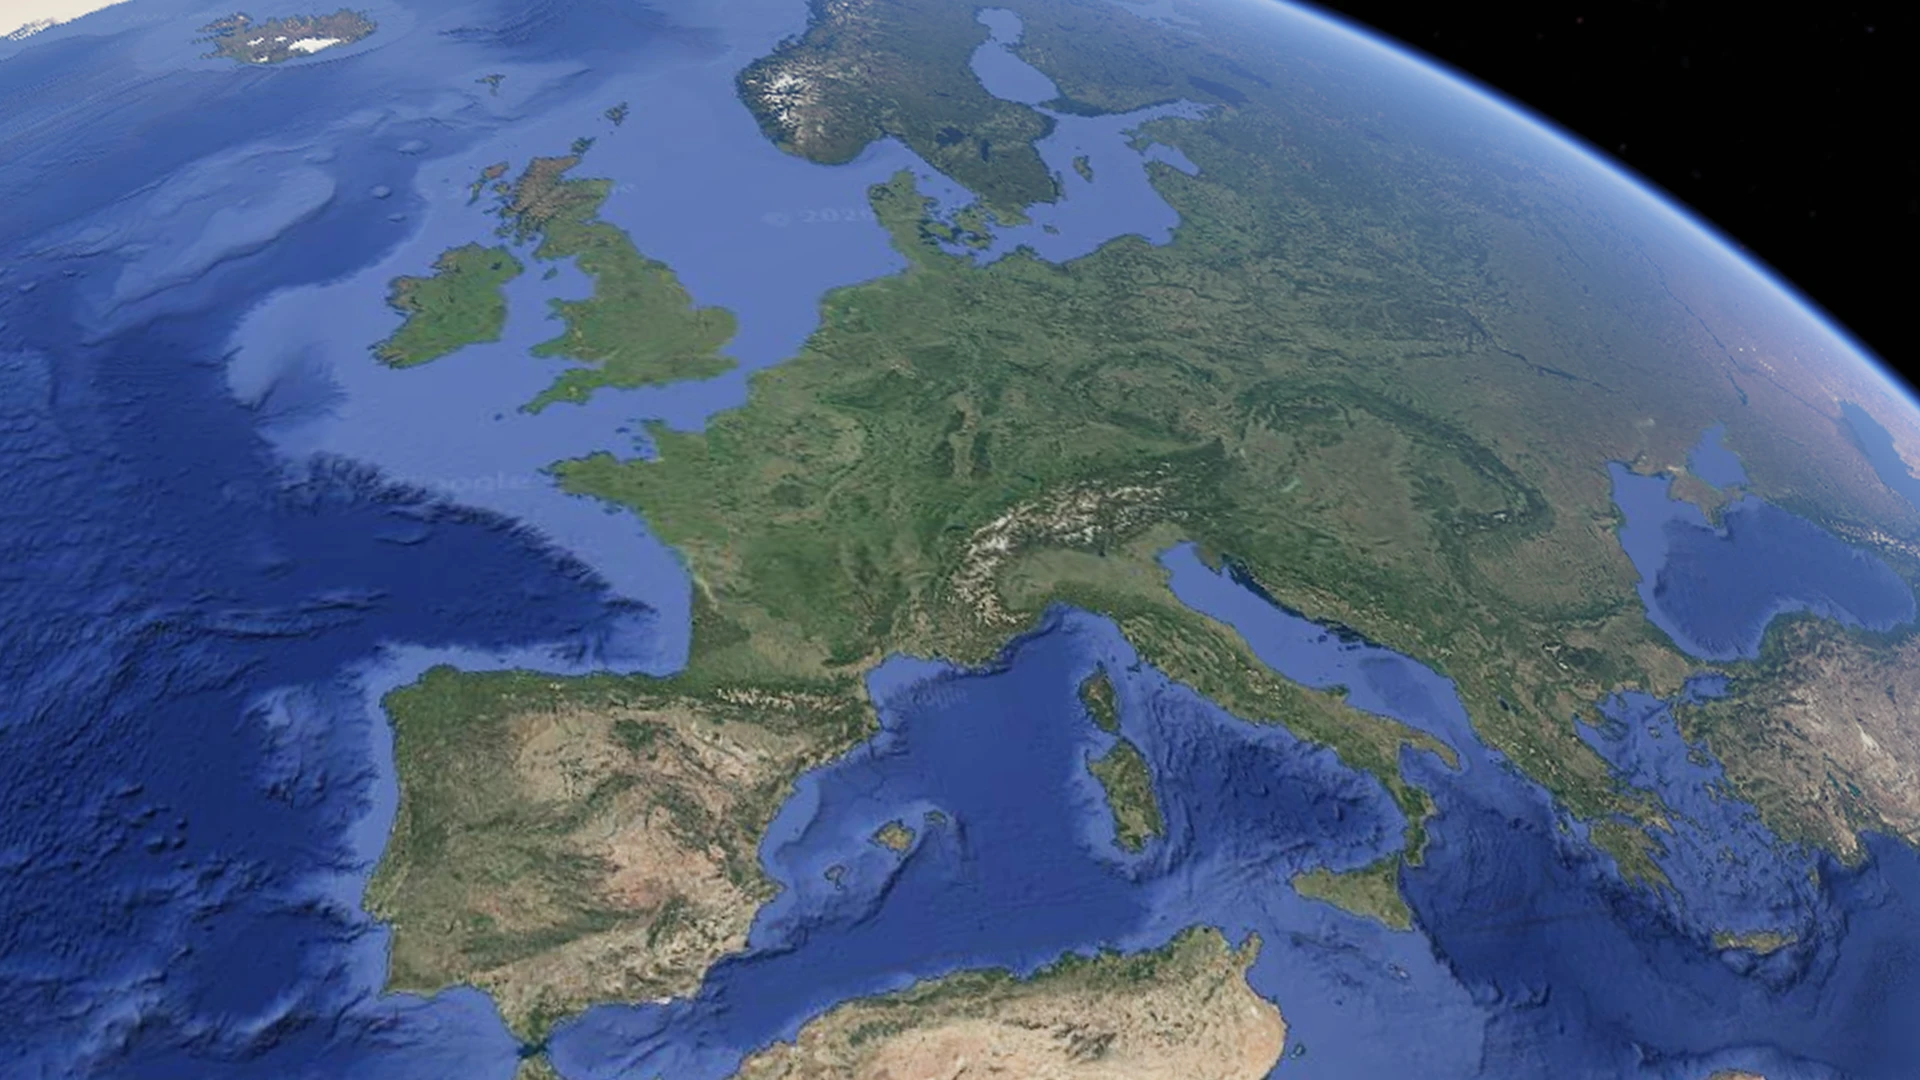
► Europe
(Google Earth)
Current Trends
European commercial property transaction volumes surpassed EUR 100 billion in H1 2026, propelled by central bank interest rate cuts, stabilising prime yields, and a surge in institutional capital targeting operational assets, nearshoring logistics, and AI digital infrastructure.
Transaction activity accelerated significantly, with Q2 volume rising 6% year-on-year to EUR 53 billion, while prime logistics yields established a solid pricing floor at 4.95% for the sixth consecutive quarter.
Monetary policy rate cuts from the European Central Bank (ECB) and the Bank of England have effectively narrowed vendor-buyer pricing expectations, unlocking delayed core-plus and value-add equity deployments, although expectations for further cuts are now on hold.
Corporate growth is overwhelmingly being delivered through joint-venture risk-sharing, co-investments, and strict balance-sheet discipline rather than financial leverage.
Opportunities
Core investment opportunities are concentrating in hyperscale AI data centres backed by grid predictability, with Paris leading regional deliveries after completing 72.5 MW in H1 2026.
Institutional capital is also expanding into scalable operational living platforms including PBSA, senior living, single-family housing, and co-living formats.
Adaptive reuse strategies targeting office-to-residential or hotel conversions continue to offer attractive value-add playbooks, while private credit funds are actively stepping in to fill persistent bank liquidity gaps.
Challenges
Development viability remains constrained across major European markets due to persistent construction cost inflation and a significant debt refinancing gap.
Digital infrastructure deployment faces major structural bottlenecks, including up to 7-to-12-year queues for high-voltage grid connections in some regions, while broader transaction volume remains exposed to ongoing geopolitical volatility.
▷ United Kingdom (UK)
Current TrendsCentral London trailing 12-month office investment reached EUR 20.4 billion (USD 22.1 billion), maintaining its second-place global ranking in European investor sentiment. Acute Grade A supply shortages pushed central office rental growth to 15.2% year-on-year, with City prime rents hitting GBP 95/sq ft, up 12%, and Mayfair and St James's reaching GBP 200/sq ft, up 18%.
AI occupiers drove substantial leasing momentum, taking up 0.7 million sq ft in H1 2026 alone and surpassing total take-up for all of 2025. Out-of-town retail parks led total returns across the commercial spectrum, underpinned by a record-low vacancy rate of 1.8%.
Opportunities
High-conviction strategies are focused on PBSA, single-family rental housing, and private credit execution. Significant equity is also targeting the recapitalisation of stressed capital stacks, alongside logistics retrofits designed to deliver high-voltage power capacity required for modern automation and electric vehicle fleets.
Challenges
Construction starts continue to be suppressed by tender price inflation, forecast at 3.5% for 2026, alongside elevated debt financing outlays. Institutional momentum is further tempered by persistent local planning backlogs, volatile gilt yields, and tax policy reforms that are accelerating high-net-worth capital exodus.
▷ Germany
Current TrendsAn orderly market stabilisation is taking hold across Germany, marked by a transaction rebound across core logistics, residential, and prime commercial assets. Berlin generated EUR 4.4 billion (USD 4.8 billion) in trailing 12-month investment, with office vacancy standing at 8.6% and rental growth rising 4.3% year-on-year.
However, major hubs continue to face structural headwinds, with Berlin ranking 14th and Frankfurt 17th in sentiment in the latest GRI Barometer from Europe GRI 2026 - Summer Edition, due to a persistent 10-15% valuation disconnect and tightened bank lending conditions under CRR III capital rules.
Opportunities
Capital is targeting Grade A CBD offices compliant with the Energy Performance of Buildings Directive (EPBD), modern urban logistics hubs in the Rhine-Ruhr and Munich corridors offering prime yields of 4.90%-5.05%, and food-anchored retail warehouses. Alternative living formats within the broader residential ecosystem also remain a primary target for income-focused equity.
Challenges
Secondary assets with high carbon intensities face severe price discounting and obsolescence. Digital infrastructure expansion is hindered by utility connection lead times in Frankfurt averaging 24 months, while the broader living sector struggles against a national housing deficit of 700,000 units, strict rent controls, and high brownfield clearance costs for unexploded ordnance.
▷ France
Current TrendsTrailing 12-month investment in the Paris office market reached EUR 14.4 billion (USD 15.6 billion), with prime rents increasing 3.3% year-on-year and overall vacancy holding at 11.8%. Occupier demand remains heavily concentrated in central business districts, driving a sharp operational divergence as peripheral office locations reprice downward.
Simultaneously, France has consolidated its role as Europe's leading AI-driven data centre hub, benefiting from grid predictability and robust nuclear energy baseloads.
Opportunities
Hyperscale data centre developments represent a standout growth sector by leveraging nuclear energy power availability and grid predictability. Additional opportunities lie in prime Paris luxury high-street retail corridors experiencing sub-3% vacancy, student housing block acquisitions, high-efficiency aparthotels, and light industrial units.
Challenges
The French real estate market has been negatively impacted by a contraction in mortgage lending amid the prevailing interest rate environment, strict carbon reduction mandates under the 2030 Décret Tertiaire, and high public debt burdens. Furthermore, secondary office properties in peripheral submarkets face accelerating structural obsolescence.
▷ Spain
Current TrendsMadrid retains its top pan-European leadership position, supported by strong national gross domestic product growth above 2%, favourable demographic inflows, and robust Grade A office and logistics space absorption across Madrid and Barcelona.
Institutional living assets dominate corporate deal flow, accounting for 61% of total merger and acquisition volume in the country.
Opportunities
Targeted investment themes include severely undersupplied PBSA assets, co-living schemes supported by digital nomad migration, luxury branded residences achieving average daily rates above EUR 1,000, BTR unit sales, and clean energy platforms focused on battery storage infrastructure.
Challenges
The Spanish property market faces a severe and accumulating structural housing shortage, projected to peak at 922,000 units by 2029, exacerbated by acute skilled labour deficits. Development activity is further delayed by six-year planning lead times, 75% land protection rules in primary metros, Catalonian rent control legislation, and high grid connection fees.
▷ Portugal
Current TrendsPortugal's commercial real estate performance is underpinned by resilient tourism fundamentals, private wealth inflows, and a prime retail recovery.
Office leasing in Lisbon and Porto is defined by a severe shortage of large, modern, ESG-certified floorplates, which continues to preserve landlord pricing power.
Opportunities
Investors are finding compelling value in the refurbishment of prime CBD office stock, student housing development, and branded residences commanding 45% pricing premiums over conventional luxury units. Long-term capital is also deploying into retail parks in secondary and tertiary cities, 25-year public-private partnerships for middle-income rental housing, and solar-retrofitted logistics space.
Challenges
Execution timelines are prolonged by municipal licensing and planning delays ranging from 12 to 36 months, against the backdrop of a 293,000-unit national housing deficit. Development viability is further strained by tender cost escalations, a 7.5% property transfer tax on non-resident purchasers, and a 2% statutory rent indexation cap.
▷ Italy
Current TrendsMarket sentiment across Italy has surged, with H1 2026 investment in the property sector reaching a record EUR 7 billion, representing a 28% increase year-on-year.
Milan office investment reached EUR 600 million in H1, representing 52% of national office volume with prime yields settling at 4.0%, as Grade A assets captured over 60% of total occupier take-up.
Meanwhile, Italian retail real estate transactions drove 36% of Q2 activity, led by prime high-street locations in Milan and Rome.
Opportunities
Primary avenues for equity deployment include Grade A transit-oriented office towers in Milan, office-to-residential or hotel adaptive reuse projects, PBSA, and flex-living platforms. Value-add investors are also targeting mid-market hotel upgrades in secondary regional markets and expanding industrial corridors across Northern Italy.
Challenges
The Italian market operates against a backdrop of subdued macroeconomic growth at 0.6% GDP and inflation at 3.1%, alongside a national housing deficit of 600,000 units. Simultaneously, lending terms remain conservative, while complex administrative permitting bottlenecks continue to slow project delivery.
▷ Central and Eastern Europe (CEE)
Current TrendsCommercial property investment across the CEE-6 economies expanded 20% year-on-year in H1 2026 to EUR 5.5 billion, anchored by Poland capturing EUR 3.06 billion, up 72% year-on-year, with Q2 posting a record volume exceeding EUR 2.0 billion.
Regional economic growth continues to outperform Western Europe by a 1.1% premium. Polish industrial performance was particularly robust, with warehouse net take-up surging 60% year-on-year to 2.1 million sqm, lowering vacancy to 6.2%, while Warsaw office take-up rose 5% with vacancy at 13.1%.
Opportunities
Key growth drivers centre on industrial nearshoring and Western European supply-chain realignment hubs. Institutional capital is also targeting regional retail parks catering to local convenience demand, build-to-sell residential schemes achieving 30-50% profit margins, and Romanian real estate offering attractive yield premiums over core markets.
Challenges
Digital infrastructure investment remains muted across CEE due to severe power accessibility bottlenecks. At the same time, the ongoing Russia-Ukraine war continues to fuel uncertainty across Eastern Europe. The region also faces a major 2026-2027 debt maturity wall, high currency swap costs for foreign equity investors, and persistent secondary office vacancy exceeding 20%.
▷ The Nordics, Netherlands, Ireland, and Greece
Current TrendsThe Nordic region has successfully transitioned from valuation stabilisation into an active capital recovery phase, with Stockholm trailing 12-month commercial investment reaching EUR 5.7 billion (USD 6.2 billion).
Amsterdam maintains its position as a core European logistics, office, and digital infrastructure hub, with colocation data centre vacancy holding steady at 6.5%.
Ireland is sustaining balanced transaction activity across Grade A Dublin office buildings, living formats, and regional digital infrastructure projects.
Opportunities
High-yielding strategies include value-add logistics platforms, luxury hospitality developments, and mixed-use urban regeneration projects in Greece, supported by strong macroeconomic expansion and record tourism.
Additional opportunities exist in regional Irish data centre developments featuring dedicated on-site renewable energy generation, alongside core Nordic and Dutch office and industrial assets.
Challenges
The Nordic market is challenged by elevated office vacancy - particularly in Stockholm, which stands at 16.1%.
In Ireland, national grid allocation frameworks are intentionally restricting digital infrastructure development within the Greater Dublin Area, redirecting capital toward regional power nodes.
► Discover all of the upcoming GRI Institute Europe events here
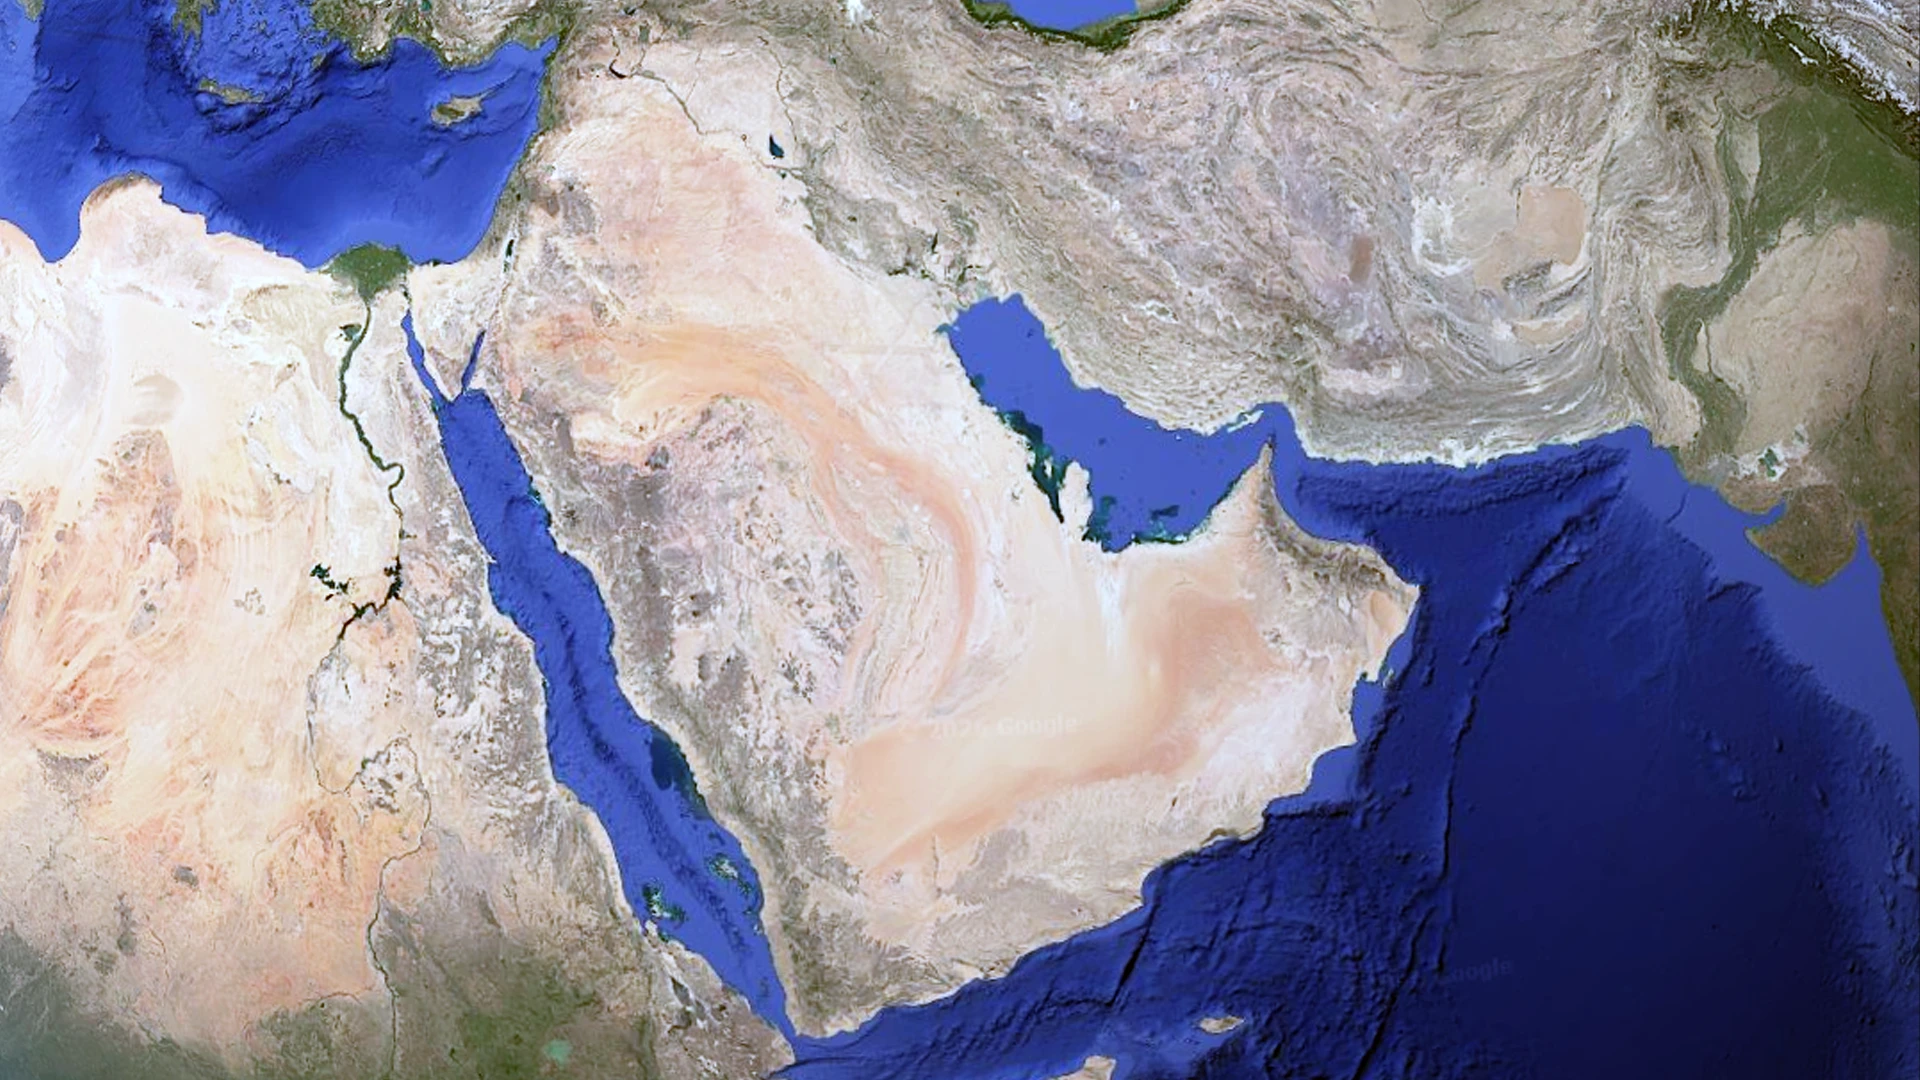
► Gulf Cooperation Council (GCC)
(Google Earth)
Current Trends
The GCC real estate market remains a high-growth hub driven by state-led economic diversification mandates, massive infrastructure deployment, and sustained structural population inflows.
Despite mid-2026 regional geopolitical friction, market activity recovered rapidly, maintaining strong transaction momentum. Headline CPI inflation across the Gulf is expected to remain contained at a manageable 2.5% in 2026 before easing to 1.8% in 2027.
Opportunities
Primary opportunities are mostly being seen in public-private joint ventures across the tourism, healthcare, and education sectors, alongside hyperscale data centres and essential infrastructure. Capital is also actively targeting strategic logistics corridors designed to bypass maritime transit bottlenecks.
Challenges
The region faces monetary drag from dollar-pegged interest rates that delay widespread monetary easing until 2027. Furthermore, supply-chain disruptions through the Strait of Hormuz continue to elevate import transport costs and freight risk profiles.
▷ United Arab Emirates (UAE)
Current TrendsTotal Dubai real estate transactions reached AED 419.9 billion in H1 2026, supported by AED 102 billion in active mortgage volume. Prime office vacancy has dropped to near-zero levels, standing at 0.7% in Dubai and 0.1% in Abu Dhabi.
Residential prices and rents are experiencing moderation from peak growth, prompting proactive tenant-focused policy interventions including Abu Dhabi's rent freeze and Dubai's Flexi Rent initiative.
Opportunities
Growth avenues centre on Grade A office redevelopments, off-plan residential brand partnerships, and industrial localisation initiatives backed by the AED 1 billion National Industrial Resilience Fund. Investors are also targeting port-adjacent logistics assets, such as DP World's East Coast terminal, alongside flexible workspace formats.
Challenges
The market faces subdued near-term international hotel RevPAR performance due to summer seasonality and regional friction. Additionally, developers are navigating construction material import delays alongside rising domestic fuel and diesel expenses.
► Join us in Abu Dhabi on 9th December for the GRI Global Summit 2026
▷ Saudi Arabia
Current TrendsVision 2030 initiatives and the RHQ mandate continue to drive immense commercial space demand, with over 780 multinational corporate headquarters established in Riyadh pushing Grade A office occupancy to 98%. In the residential segment, average villa prices in Riyadh rose over 5% year-on-year to approach SAR 6,000 per square metre.
Opportunities
Institutional capital is pursuing private-sector JVs through the Tourism Development Fund and acquiring trophy office assets within the King Abdullah Financial District (KAFD). Strategic opportunities also exist in MODON industrial city developments across Makkah and Al Kharj, alongside prime luxury residential projects.
Challenges
The Kingdom faces an acute structural deficit of Grade A office accommodation, with a near-term delivery pipeline of only 570,000 square metres. Operational execution is further hampered by hospitality knowledge-transfer gaps and extended regional supply-chain disruption risks.
▷ Qatar
Current TrendsMarket institutionalisation and regulatory transparency have improved significantly across Qatar, positioning the country among the top global improvers in real estate transparency index rankings. Downstream economic demand generated by the massive North Field LNG expansion project is progressively absorbing post-World Cup residential and hospitality inventory.
Opportunities
Key targets for institutional deployment include prime Grade A office accommodation in Lusail and West Bay. Strong opportunities are also emerging in modern distribution parks supporting light manufacturing and logistics assets directly linked to Hamad Port.
Challenges
The domestic economy is dealing with accelerated food import inflation caused by maritime shipping disruptions through the Strait of Hormuz. In addition, secondary residential submarkets continue to contend with lingering structural oversupply.
▷ Bahrain
Current TrendsCommercial property leasing fundamentals in Bahrain remain steady, underpinned by a highly cost-competitive operational environment. Market activity is heavily reinforced by direct causeway logistics integration with Saudi Arabia's Eastern Province.
Opportunities
High-priority growth areas include modern warehousing facilities surrounding Bahrain International Airport and Khalifa bin Salman Port. Additional capital is deploying into corporate office space for regional wealth management and fintech firms, alongside specialised industrial parks.
Challenges
The market is impacted by subdued residential capital growth and transport-driven inflation following retail fuel price liberalisation. Logistics operators must also navigate an increased reliance on costlier land and air freight during maritime shipping disruptions.
▷ Kuwait
Current TrendsKuwait's macroeconomic conditions are rebounding effectively, with headline CPI inflation remaining well contained at 2.4% in 2026. Price stability is being actively maintained through government food-import insurance programmes and strict regulatory price controls.
Opportunities
Investors are targeting high-quality, income-producing commercial real estate assets, alongside modern logistics facilities structured to support domestic retail consumption. Selective opportunities also exist in targeted, high-end residential developments.
Challenges
Private sector operators face input-cost inflation reaching multi-month highs, combined with restrictive commercial debt underwriting conditions. Ongoing regional supply-chain uncertainty continues to weigh on broader corporate sentiment.
▷ Oman
Current TrendsHydrocarbon revenue gains and strategic Vision 2040 investments continue to support broader economic expansion across Oman. Logistics networks are benefiting as international traders increasingly re-route cargo overland through Omani territory to bypass regional maritime chokepoints.
Opportunities
Investment is expanding rapidly in port-led industrialisation and strategic logistics nodes that leverage direct maritime access outside the Strait of Hormuz. Infrastructure development projects backed by international funding initiatives offer further long-term capital deployment avenues.
Challenges
The Sultanate faces a sharp spike in annual food inflation - reaching 7.3% in mid-2026 - driven by elevated regional maritime risk surcharges and global shipping route realignments. While overland transit corridors and Indian Ocean ports effectively absorb freight bypass traffic around the Strait of Hormuz, domestic food supply chains remain vulnerable to carrier schedule disruptions and shallow fiscal reserve buffers.
► View our upcoming GRI Institute events in the GCC region here
► Latin America
(Google Earth)
Current Trends
Latin American real estate markets are undergoing a fundamental transformation driven by industrial nearshoring, agribusiness export infrastructure, and structural urban housing demand.
Institutional capital is increasingly prioritising market transparency, regulatory clarity, and operational yield over speculative capital appreciation. Across major regional gateways, investment activity is shifting towards defensively structured real assets that offer long-term inflation protection and resilient cash flows.
The macroeconomic environment across the region is characterised by monetary policy adjustments, with several central banks navigating interest rate cycles while seeking to preserve capital stability amid broader global economic shifts.
Opportunities
Primary opportunities across the region are found in strategic logistics corridors directly linked to international trade routes, advanced manufacturing hubs, and power-ready land for expanding digital infrastructure.
Institutional allocators are actively deploying capital into purpose-built multifamily living platforms designed to address chronic regional housing deficits, as well as public-private infrastructure joint ventures that enhance regional connectivity and supply chain integration.
Challenges
The regional property sector faces ongoing operational hurdles stemming from volatile borrowing costs, strict domestic mortgage underwriting standards, and acute energy and water infrastructure bottlenecks. Furthermore, persistent political and regulatory uncertainty in select markets, combined with construction cost inflation, continues to complicate long-term project underwriting and extend development timelines.
▷ Brazil
Current TrendsIn the Brazilian real estate market, prime Grade A office space in São Paulo's core submarkets, specifically Faria Lima, Itaim Bibi, and Pinheiros, is recording sustained space absorption and consistent rental growth.
In the industrial segment, modern logistics vacancy within a 30-kilometre radius of core urban centres sits below 6%, reflecting tight supply conditions and sustained occupier demand.
Capital deployment across real estate sectors is being supported by Selic interest rate easing, active listed real estate investment funds (FIIs), and domestic family offices expanding their allocations into real asset strategies to secure long-term yield.
Opportunities
High-conviction investment strategies are targeting power-ready land parcels for data centre campus expansions, alongside Grade A urban-ring logistics parks optimised for fast-mile distribution. Institutional investors are also expanding into purpose-built institutional multifamily rental assets, as well as interior land subdivisions (loteamentos) designed to capture expanding suburban housing demand across secondary markets.
Challenges
Brazil's residential sector remains constrained by an underdeveloped institutional rental market despite the presence of millions of tenant households. Developers and fund managers must also navigate borrowing cost volatility that directly impacts project internal rates of return (IRRs), alongside emerging governance requirements for artificial intelligence (AI) integration within project development and asset management workflows.
► Don’t miss Brazil GRI 2026 on 28th-29th October in Sao Paulo
▷ Mexico
Current TrendsMexican real estate remains the primary beneficiary of USMCA-driven supply chain nearshoring, maintaining industrial vacancy below 2% across key northern border hubs, including Monterrey, Ciudad Juárez, and Tijuana.
Real estate investment trusts (FIBRAs) and US cross-border equity are actively funding logistics facilities, advanced manufacturing plants, and urban mixed-use assets. Concurrently, booming domestic and international tourism continues to drive significant capital into luxury hospitality and branded living developments.
Opportunities
Primary avenues for equity deployment include advanced manufacturing facilities, strategically located northern border logistics corridors, and luxury branded residential developments in Mexico City and prime northern metropolitan hubs. Furthermore, there is growing institutional demand for nearshoring-linked residential developments designed to accommodate expanding industrial workforces.
Challenges
Market expansion is increasingly constrained by severe energy grid capacity limitations and water infrastructure bottlenecks, which directly dictate tenant retention and park viability. Developers must also navigate policy and trade uncertainty, alongside high construction material price inflation that places upward pressure on development budgets.
▷ Chile
Current TrendsChile maintains its position as one of Latin America's most institutionalised property markets, underpinned by deep domestic pension fund allocations, highly transparent legal frameworks, and disciplined core asset yields.
The Santiago office market is demonstrating sustained stabilisation, with leasing activity and tenant retention concentrating in prime submarkets such as Las Condes and Providencia.
Opportunities
Institutional capital is targeting purpose-built multifamily rental assets (multifamiliar) engineered to address growing middle-income housing demand in urban centres. Strategic opportunities also exist in modern logistics assets directly integrated with primary mining operations and international maritime trade corridors.
Challenges
The residential sector is facing headwinds from strict private mortgage underwriting standards that continue to constrain homeownership rates. Additionally, institutional developers face extended environmental permitting backlogs and complex operational hurdles when scaling unified multifamily management platforms.
▷ Colombia
Current TrendsColombia has established itself as a global leader in real estate transparency improvement following the comprehensive digitisation of its land records, cadastral registers, and municipal zoning frameworks.
Office space take-up in Bogotá and Medellín remains positive, propelled by multinational corporate expansions, nearshore business process outsourcing (BPO) operations, and growing demand for flexible workspaces.
Opportunities
Investment interest is concentrated in modern logistics parks along the critical Bogotá-Cundinamarca corridor servicing e-commerce fulfilment, alongside integrated urban mixed-use developments. Capital is also deploying into government-backed affordable housing initiatives designed to bridge structural supply gaps.
Challenges
The real estate market operates against a backdrop of national fiscal budget imbalances and substantial qualitative and quantitative housing deficits. Construction activity is further impacted by persistent inflationary pressure on building materials and specialised labour outlays.
▷ Peru
Current TrendsMajor national infrastructure investments are driving robust logistics space absorption across Peru, highlighted by the operational expansion of the Chancay Megaport corridor north of Lima.
In Metropolitan Lima, Grade A office vacancy is progressively compressing towards historic equilibrium levels, while retail parks continue to generate stable footfall and resilient operational revenues.
Opportunities
Capital deployment is targeting industrial land acquisitions and logistics developments strategically located along marine trade corridors. Additional value exists in modern retail parks serving suburban consumer catchments, as well as urban multifamily residential developments located across central Lima districts.
Challenges
The broader investment climate continues to contend with political unpredictability and persistent market illiquidity, which restricts large-scale institutional entry. Furthermore, monetary policy caution tied to global inflation risks continues to slow long-term capital deployment decisions.
▷ Argentina
Current TrendsAn early-stage institutional asset repricing is taking shape across Argentina, supported by wide-ranging economic deregulation, reduced currency volatility, and broader inflation stabilisation. Private transaction activity is increasing across prime Buenos Aires commercial properties, as well as high-grade agricultural land holdings.
Opportunities
Key growth vectors include agribusiness-linked logistics and regional distribution networks, opportunistic commercial asset acquisitions at historically attractive valuation baselines, and private wealth capital deployment into defensive real assets.
Challenges
The real estate sector is contending with a sharp contraction in domestic mortgage lending, which has resulted in a sluggish residential sales market. International and domestic investors must also manage historical macroeconomic fluctuations and structural currency volatility risks.
▷ Uruguay
Current TrendsUruguay continues to serve as a stable regional financial and capital haven, leveraging its solid credit ratings to consistently draw technology enterprises, regional corporate headquarters, and private wealth allocations seeking long-term capital preservation.
Opportunities
Investment interest is focused on luxury residential schemes, boutique office projects in prime Montevideo business districts, and family office wealth preservation structures focused on prime commercial real assets.
Challenges
Real estate operators face elevated living and operational outlays relative to neighbouring regional economies. Furthermore, the compact overall scale of the domestic market limits large-scale institutional liquidity and rapid portfolio expansion.
▷ Paraguay
Current TrendsParaguay is attracting sustained cross-border capital inflows from neighbouring economies, establishing itself as an increasingly tax-competitive jurisdiction for high-net-worth individuals, mobile corporate capital, and regional developers.
Opportunities
Strategic investment avenues centre on agribusiness logistics infrastructure, modern industrial warehousing, and high-quality residential developments designed to meet growing urban demand in Asunción.
Challenges
The domestic market continues to develop its institutional property management and regulatory frameworks. Additionally, the local economy remains inherently vulnerable to macroeconomic cycles and policy shifts in neighbouring Brazil and Argentina.
▷ The Caribbean
Current TrendsStrong institutional and private equity capital flows continue to target high-end resort hospitality assets and luxury branded residential communities across the Caribbean, driving record per-square-foot transaction valuations in prime island destinations.
Opportunities
High-conviction strategies are concentrating in climate-resilient infrastructure developments, luxury branded residential schemes offering managed rental programmes, and ultra-high-net-worth resort developments.
Challenges
The region faces elevated vulnerability to extreme climate and severe weather events, alongside a heavy structural reliance on imported construction materials. Furthermore, performance across the hospitality and residential sectors remains highly sensitive to international travel sentiment and broader global economic conditions.
► See all upcoming GRI Institute events in Latin America here
► United States (US)
(Google Earth)
Current Trends
The US commercial real estate market in late 2026 is transitioning into an income-driven phase of stabilisation, where bottoming valuations, declining Treasury yield volatility, and an AI-driven digital infrastructure boom are accelerating capital markets transaction volume.
Total industrial net absorption reached 113.6 million square feet in H1 2026, lowering national vacancy to 6.9% as net tenant demand outpaces new supply deliveries.
Core multifamily properties are experiencing annual rental growth stabilising in the 2.8% to 3.3% range as new apartment completions taper off.
National office leasing volumes reached post-pandemic highs in mid-2026, led by trophy Class A properties, with prime gateway CBD office vacancy stabilising between 12% and 15%. Conversely, secondary commodity suburban office assets face vacancies exceeding 20%, with capitalisation rates remaining elevated between 9% and 13%.
Opportunities
High-conviction investment opportunities are concentrating in generative AI digital infrastructure, specialised build-to-suit logistics facilities, defensive healthcare and medical outpatient assets, and the recapitalisation of core multifamily platforms as new supply deliveries subside.
Challenges
Market participants face persistent headwinds from higher-for-longer borrowing costs, severe power grid transmission constraints delaying project completions, refinancing shortfalls across legacy secondary office stock, and stringent lender debt underwriting.
▷ East Coast
Current TrendsPositive demographic net migration, corporate relocations, and major infrastructure capital investments continue to underpin steady regional demand.
In New York, trailing 12-month commercial investment reached USD 36.4 billion in mid-2026, with office vacancy tightening to 13.0% and prime rents advancing 4.1% year-on-year.
In Atlanta, trailing 12-month commercial property investment reached USD 17.9 billion, though metropolitan office vacancy remains elevated at 26.3% due to legacy suburban commodity stock.
In Florida and North Carolina, metropolitan centres including Miami, Fort Lauderdale, Charlotte, and Raleigh are experiencing steady multifamily absorption, with rental growth recovering to a sustainable 2.8% to 3.2% range as heavy 2023-2024 construction completions are digested.
The Mid-Atlantic data centre market, anchored by Northern Virginia, remains the largest concentration of digital infrastructure globally, where hyperscale operators are acquiring land and securing power purchase agreements for generative AI workloads.
Opportunities
Primary avenues for equity deployment include hyperscale data centre expansion into power-adjacent submarkets, port-adjacent logistics corridors such as the Port of Savannah, necessity-anchored suburban retail centres, and luxury living formats.
Challenges
The subregion faces development delays from power grid transmission bottlenecks requiring secured substation interconnections, persistent vacancy drag from legacy commodity suburban office stock, and localised rental concessions.
▷ Midwest
Current TrendsThe Midwest property market offers defensive cash-flow yields, institutional stability, and exposure to domestic manufacturing revitalisation and nearshoring.
Industrial and logistics fundamentals across the Midwest are performing strongly, with Chicago recording 21.8 million square feet of gross leasing activity in H1 2026, ranking third nationally.
Strategic logistics nodes across Columbus, Indianapolis, and Kansas City continue to attract third-party logistics providers and industrial manufacturers restructuring domestic inventory networks.
The office sector across Midwestern metropolitan centres is seeing a distinct operational bifurcation, with obsolete Class B office towers undergoing adaptive reuse conversions while trophy riverfront and medical district towers capture stable leasing.
Opportunities
Growth vectors centre on adaptive reuse conversions of obsolete Class B office towers into residential or mixed-use formats, advanced manufacturing facilities, and medical outpatient real estate assets.
Challenges
Operators must navigate slower net population growth compared to Sunbelt hubs, localised sublease space in legacy industrial properties, and high capital costs associated with complex building conversions.
▷ South Central & Southwest
Current TrendsThe South Central and Southwest markets are navigating a transition from supply-driven construction booms into a phase of fundamental space absorption.
Dallas-Fort Worth established itself as the leading logistics market in the United States, recording 40.3 million square feet of gross industrial leasing (generating +13.6 million square feet of net absorption) during H1 2026, with trailing 12-month commercial investment reaching USD 18.5 billion.
In the residential living sector across Texas (Dallas, Austin, and Houston) and Arizona (Phoenix), the substantial supply wave of new multifamily units that pressured rents throughout 2024 and 2025 has largely cleared, setting the stage for steady rent growth.
Concurrently, Phoenix and Central Texas continue to attract advanced semiconductor manufacturing clusters, technology logistics, and hyperscale data centre investments.
Opportunities
Strategic targets include advanced semiconductor manufacturing clusters, technology logistics hubs, BTR housing developments, and behind-the-meter power solutions for data centres.
Challenges
The market is impacted by near-term rent softening in recently oversupplied residential submarkets, legacy office vacancy drag, and land price inflation caused by data centre land acquisition premiums.
▷ West Coast
Current TrendsWest Coast property markets are exhibiting an operational turnaround, led by corporate expansions from the artificial intelligence ecosystem and steady port-adjacent industrial absorption.
The Inland Empire recorded 28.5 million square feet of gross industrial leasing in H1 2026, benefiting from normalised retail container volumes across the Ports of Los Angeles and Long Beach.
In the office sector, San Francisco recorded positive net absorption in Q2 2026, supported by venture-backed generative AI enterprises expanding their physical office footprints, with direct investment reaching USD 9.6 billion over the trailing 12 months.
Meanwhile, the Puget Sound and Southern California life sciences sectors have entered a stabilisation phase, with tenant leasing picking up across modern research campuses.
Opportunities
High-conviction strategies are targeting prime, highly amenitised trophy office towers capturing corporate expansions, port-adjacent last-mile logistics networks, and modern laboratory research campuses.
Challenges
Execution is constrained by high total office vacancy driven by legacy technology sublease inventory, elevated lab space availability, complex urban entitlement processes, and high operating expenses.
► Check out upcoming GRI Institute events in North America here
Conclusion
As commercial real estate closes out 2026, global property markets are transitioning from a period of pricing discovery into an era defined strictly by operational execution.Macroeconomic stability and clearer monetary policy offer a firmer foundation for capital deployment, yet market performance through Q4 2026 and beyond will depend on asset-level resilience rather than broad cyclical tailwinds.
Looking ahead, the line between prime real estate and legacy stock will widen further. Securing infrastructure access - particularly grid connectivity and power baseloads - has become as critical as location for logistics and digital assets, while retrofitting secondary assets is now an urgent operational necessity to prevent obsolescence.
Institutional allocators will increasingly favour direct transactions, co-investment joint ventures, and flexible debt structures to maintain governance and mitigate risk.
Ultimately, sustainable long-term value will belong to market participants who align their capital with enduring structural demand drivers - digital transformation, nearshoring logistics, and severe urban living deficits.
► The GRI Global Summit in Abu Dhabi on 9th December will convene senior decision makers from around the world - event details here
► Check out all upcoming GRI Institute gatherings on our full calendar
Sources:
Allianz
CBRE
Colliers
Cushman & Wakefield
Deloitte
Economic Times
Fitch Solutions
GRI Institute
IMF
JLL
Knight Frank
Morgan Stanley
OECD
Reuters
Savills
Schroders
Vision 2030