 GRI Institute
Scaling Italian Real Estate: Can €7 trillion in private wealth reduce reliance on international capital?
Exclusive GRI Institute insights on scaling capital, operational platform integration, and mobilising domestic private wealth across Italian real estate
Executive Summary
Favourable yield spreads, valuation stability, and relative macroeconomic calm are driving a sharp capital recovery across Italian commercial real estate. However, deploying capital at scale requires a clear shift from passive property acquisitions toward vertically integrated operating platforms.
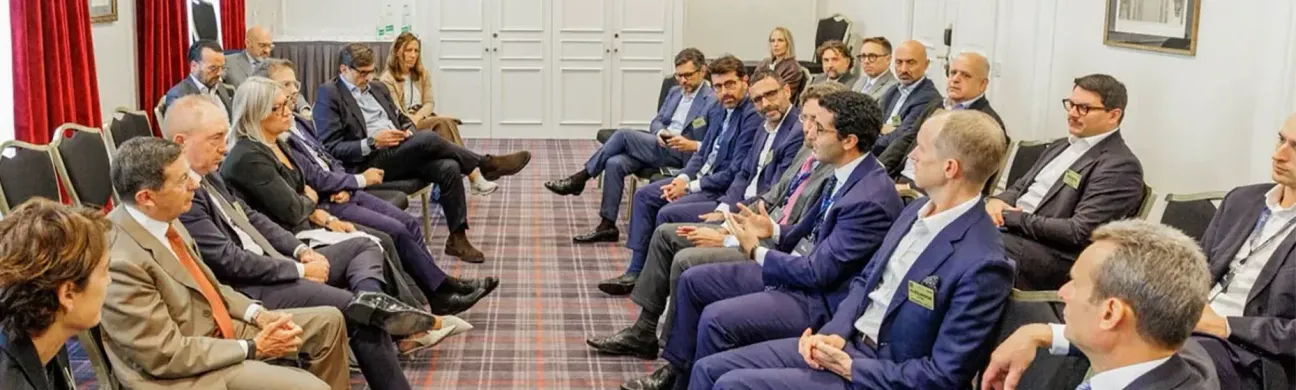
These overarching themes shaped the conversation during the Italy: Can Capital Scale Up? panel at the Europe GRI 2026 - Summer Edition summit. The debate underscored that achieving institutional scale relies far less on broad market timing and much more on securing local operational alignment.
The challenge of tapping domestic wealth channels and building resilient local partnerships will take centre stage at the Italy: Private Capital vs Institutional Investors roundtable, co-hosted by Fivers in Milan on 24th November, where industry leaders will reassemble to map out the next phase of market expansion.
► Check out full details of the Italy Private Capital vs Institutional Investors roundtable here
► Read the full Europe GRI 2026 - Summer Edition Spotlight report here
Key Takeaways
- Relative political stability, resilient asset valuations, and favourable yield spreads over core European markets are driving a strong capital recovery in Italian real estate.
- Scaling deployment requires a pivot from passive property acquisitions toward vertically integrated operating platforms to control construction supply chains and secure execution.
- Overcoming granular lot sizes, administrative hurdles, and cross-border dependence hinges on partnering with local operational aggregators and unlocking domestic private wealth.
Macroeconomic Stability and the Valuation Divergence
The Italian commercial real estate market is experiencing a pronounced capital recovery, highlighted by first-half transaction volumes reaching EUR 7.7 billion. This figure represents a 44% surge over the previous semester and stands 72% above the ten-year half-year benchmark, signalling a major structural expansion.
A key catalyst behind this momentum is the macroeconomic and political stability currently characterising the jurisdiction. While core Western European markets struggle with fiscal friction, elevated inflation, and severe valuation write-downs, peripheral Southern European economies are reaping the rewards of previous structural reforms.
This relative stability has created a stark divergence in asset pricing across the continent. Property valuations in Italy have proven notably resilient, avoiding the sharp capital value corrections seen in Northern European markets.
For long-term institutional allocators, sovereign wealth funds (SWFs), and open-ended vehicles, this valuation stability offers downside protection and insulation from short-term portfolio volatility.
Furthermore, prime yields in Italy maintain a favourable spread of 50 to 100 basis points over core Western European benchmarks. In prime logistics, for instance, Italian yields hover around 5.5%, compared to approximately 4.5% in Germany, delivering a strong income buffer against elevated global borrowing costs.
Cross-border liquidity is further encouraged by the country's institutional fund framework. Specialised, transparent fund structures (such as specialised real estate investment funds and SICAFI vehicles) provide complete tax efficiency at the vehicle level for white-listed international investors.
These structures allow allocators to execute portfolio unit rotations without triggering heavy local property transfer taxes.
This mechanism contrasts sharply with tightening fiscal regimes in jurisdictions like the Netherlands, and Germany, where transfer taxes and fund unit transaction penalties have systematically increased.
Merging Real Estate with Operational Execution
Deploying capital at scale requires a departure from traditional, passive real estate acquisition strategies. Direct property investments, often described as pure brick-and-mortar plays, are increasingly viewed as yield-compressed and restrictive when executed without operational control.
To overcome severe supply deficits and secure execution certainty, institutional allocators are shifting toward combined property company (PropCo) and operating company (OpCo) models, alongside the direct acquisition of local operational and development platforms.
By acquiring established local development entities and general contractors, institutional capital secures direct oversight of construction supply chains, labour costs, and delivery timelines.
In practice, owning an integrated development platform eliminates an entire layer of intermediary profit margins. This vertical integration provides a crucial advantage in managing development risks, allowing institutional managers to source, construct, and stabilise assets internally rather than relying on competitive, highly priced public tenders.
However, this shift toward platform investing has sparked an active debate regarding the alignment of interest between asset owners and operational partners. Capital allocators point out that traditional general partner co-investments of 5% do not provide adequate risk alignment when managing complex operational platforms.
To resolve this contention, market participants are establishing joint ventures directly within the operating company equity. Under this framework, institutional investors participate in the enterprise value creation of the operational business alongside the terminal value of the real estate, aligning operations toward sustainable cash flow generation.
Operational Real Estate and Sectoral Diversification
Investment activity is undergoing unprecedented diversification, with capital expanding far beyond traditional office assets into high-demand operational sectors.
The hospitality industry, in particular, is undergoing a generational recapitalisation. Historically, the market has been dominated by family-owned, highly fragmented hotel assets.
As third-generation family members pivot away from active hotel management, an unprecedented volume of trophy assets and regional portfolios is transitioning toward institutional platforms and global brand management.
Capital deployment is also expanding beyond primary gateway cities into resort destinations across Southern Italy, and Sicily. In these secondary and resort markets, developers frequently blend hotel modernisations with luxury residential villa developments, using upfront residential sales to offset overall capital expenditure.
In the residential and living sectors, capital allocation is driven by acute structural supply-demand imbalances. Purpose-built student accommodation (PBSA) faces an extreme national undersupply, with provision rates sitting near 4% despite rising university enrolments and an expanding influx of international students.
Demand for quality living accommodation extends into urban rental housing and hybrid hospitality formats across major economic hubs, secondary university towns, and growing regional centres.
Logistics and industrial real estate remain primary targets for institutional capital, supported by strong tenant demand, local manufacturing, and supply chain reshoring trends. Modern logistics development, however, faces stringent land consumption regulations, forcing developers to prioritise complex brownfield redevelopments.
Concurrently, digital infrastructure has emerged as a major capital destination, highlighted by multi-hundred-million-euro commitments in first-half transaction volumes. Yet, data centre expansion faces major infrastructure bottlenecks.
National grid connection requests far exceed actual available power capacity, turning power access into a competitive bottleneck that requires careful technical and municipal planning.
Administrative Friction and Granular Lot Sizes
Despite expanding institutional appetite, scaling capital deployment across the Italian peninsula faces persistent operational hurdles. Lot size fragmentation represents a primary obstacle for large-scale international managers.
Approximately 80% of regional property transactions involve ticket sizes below EUR 15 million. For institutional investors managing multi-billion-euro deployment mandates, executing dozens of individual, low-value deals is resource-prohibitive.
Consequently, capital deployment depends on establishing partnerships with local operational aggregators capable of assembling granular, mid-market assets into institutional-grade portfolios.
Administrative and regulatory friction further complicates execution. Navigating urban planning permissions, brownfield environmental remediation, and utility interconnections requires navigating over eight thousand distinct municipal jurisdictions, each operating with localised administrative procedures.
Successful execution requires specialised local administrative legal expertise to manage planning agreements and municipal interactions without triggering extended project delays.
A broader structural challenge is the origin of market capital. Due to the absence of a large domestic private pension fund system, transaction liquidity remains heavily reliant on international cross-border capital, which accounts for nearly three-quarters of total transaction volume.
This heavy dependence on international capital leaves liquidity vulnerable to global macroeconomic shifts. To establish deeper domestic market liquidity, institutional asset managers are working to tap into domestic private wealth channels and family offices.
Unlocking Italy's domestic wealth, which includes over EUR 1.3 trillion sitting in idle bank accounts and EUR 7 trillion in total private wealth, requires creating transparent, tax-efficient investment vehicles tailored specifically to domestic private investors.
Outlook for Capital Allocation
The transition of Italian commercial real estate from an opportunistic, asset-by-asset market into a mature, platform-driven institutional destination is well underway.
While administrative fragmentation, small lot sizes, and a reliance on cross-border capital present ongoing operational challenges, the underlying market fundamentals remain strong.
Favourable yield spreads, valuation stability, and severe supply deficits across operational real estate sectors offer long-term risk-adjusted returns.
Institutional allocators that successfully establish vertically integrated platforms, secure local operational capabilities, and tap into domestic private wealth will be best positioned to scale capital effectively and capture long-term growth across the peninsula.
► Access the full Europe GRI 2026 - Summer Edition Spotlight report here
These insights were shared at the “Italy: Can Capital Scale Up?” panel at Europe GRI 2026 - Summer Edition, moderated by Valeria Falcone (Colliers), with panellists Andrea Imperatore (ADD Capital), Cristiano Stampa (Invesco), David Brogi (Generali Real Estate SGR), Donato Piscuoglio (Borio Mangiarotti REIM), Giulio Bentivoglio (KERVIS), and Marco Grassidonio (Garbe Industrial Real Estate).