 Gemini
How a new era of student mobility is unlocking major European living markets
Exclusive insights from Europe GRI 2026 on asset bifurcation, brand power, and capital trends across UK and Continental European PBSA markets for Q4 and beyond
October 1, 2026Real Estate
Written by:Rory Hickman
Executive Summary
Elevated replacement costs, contracting HMO supply, and legacy asset obsolescence are widening the performance gap across European PBSA. As post-pandemic demand spikes normalise across the UK and Continental Europe, institutional capital is concentrating on prime, amenity-rich platforms while outdated properties suffer pronounced vacancy drops.
These core market dynamics dominated discussions among senior decision-makers during the PBSA panel at Europe GRI 2026 - Summer Edition in Paris. What surfaced was a sector shaped not by declining occupier appetite, but by an increasingly complex operational and underwriting landscape where micro-location selection, brand equity, and design efficiency dictate long-term returns.
These shifting market realities pave the way for upcoming GRI gatherings - including the Spanish Housing & Flexible Living Models roundtable in Madrid on 11th November, the Portuguese Hospitality & Residential Investments roundtable in Lisbon on 30th November, and the Europe GRI 2027 - Winter Edition summit in London on 24th February - where industry leaders will reassemble to continue discussing capital deployment, operational integration, and relative value across European real estate sectors.
► Check out the full calendar of upcoming GRI Institute Europe events
► Read the full Europe GRI 2026 - Summer Edition Spotlight report here
Key Takeaways
- The UK PBSA sector is undergoing a post-pandemic demographic reset, with performance bifurcating sharply between prime assets and obsolete legacy stock.
- Continental European markets offer distinct structural growth driven by low provision rates, expanding English-taught courses, and tax-efficient SPV structures.
- High delivery expenses and contracting HMO supply are locking in long-term occupier demand for institutional platforms offering premium operational amenities.
► PBSA Today
(GRI Institute)
The European Purpose-Built Student Accommodation (PBSA) sector is navigating a complex period of structural transition, defined by diverging market maturities, shifting student mobility patterns, and ongoing macroeconomic adjustment.
Across both mature and emerging jurisdictions, real estate fundamentals are being tested by elevated borrowing costs, yield expansion, and rising operational expenditures.
While established markets undergo a necessary rebalancing following post-pandemic demand surges, Continental European markets present distinct growth opportunities driven by low structural provision rates, expanding English-taught academic programmes, and evolving occupier expectations.
Rather than viewing Europe as a monolithic asset class, institutional investors and operational platforms must evaluate opportunities on a city-by-city and asset-by-asset basis, balancing localised purchasing power against replacement costs and execution risks.
► UK PBSA Market Dynamics
In the UK, student housing is experiencing a cyclical rebalancing as post-pandemic demand spikes normalise across major university cities. A contraction in postgraduate international student enrolments over recent years has exerted downward pressure on occupancy rates and rental growth, creating short-term headwinds.Industry sentiment remains divided on whether this shift reflects a permanent decline or a temporary demographic reset. The prevailing consensus suggests a correction toward a new baseline that remains above pre-pandemic levels, rather than a structural downturn.
Broader market confidence has also been dampened by listed Real Estate Investment Trust (REIT) platforms that mismanaged occupancy messaging, causing public market corrections that temporarily tarnished sentiment across private portfolios.
Beneath these macroeconomic factors lies a severe structural bifurcation between prime, modern schemes and outdated legacy stock.
A central point of contention involves the timeline of physical and operational obsolescence. While some market players contend that assets built just five years ago struggle against newly delivered schemes, others argue that well-located five-year-old properties maintain full occupancy, placing true obsolescence on ten- to twenty-year-old assets.
Legacy properties that lack en-suite bathrooms, offer basic loose furniture, or feature undersized communal spaces suffer pronounced vacancy drops.
Occupiers demonstrate significant price insensitivity when evaluating quality, frequently bypassing cheaper rooms priced at GBP 180 per week in favour of modern schemes at GBP 210 to GBP 230 per week that offer superior amenities and operational standards.
This operational divide aligns closely with underlying student demographics. Premium, modern properties primarily attract international occupiers, whereas domestic students generally target lower price points at or below GBP 130 to GBP 150 per week.
When outdated, non-en-suite stock represents the only option within that affordable threshold, domestic students increasingly choose to live at home, shrinking the overall tenant base.
Repositioning these outdated assets presents substantial hurdles, as investors often misjudge the complexity of refurbishments.
Reconfiguring non-en-suite layouts requires major structural work, updated planning permissions, and navigating strict building safety gateways, making deep retrofits as complex, costly, and time-consuming as ground-up developments.
Consequently, many first-generation assets require complete site demolition and redevelopment to remain competitive.
► UK Supply Dynamics
(GRI Institute)
Ground-up development in regional UK cities has slowed dramatically as soaring construction inflation and elevated financing costs push delivery expenses above completed capital values.
Rebuilding a top-tier regional asset can cost between 20% and 30% more than its current market value, illustrated by schemes built for GBP 75 million that would require GBP 100 million to reconstruct today.
As a result, ground-up development pipelines in regional markets have contracted significantly despite land prices falling by 50% over a three-year period. Restrictive local planning regulations and high upfront planning risks further constrain overall new supply across the country.
New development remains financially viable primarily in London, where weekly rents reaching GBP 350 to GBP 500 absorb elevated delivery costs.
At the same time, the secondary supply of traditional student housing provided by Houses in Multiple Occupation (HMO) properties is contracting under regulatory pressure.
Local planning restrictions, licensing constraints, tax changes, and legislative reforms surrounding tenants' rights prevent the creation of new HMO properties while accelerating the exit of private landlords.
Once an HMO property loses its operating licence or transitions to non-student residential use, it cannot easily re-enter the student market. This permanent shrinkage in traditional housing stock provides a long-term structural tailwind for institutional PBSA platforms, locking in tenant demand even as total student enrolment figures stabilise.
► Continental European PBSA Fundamentals
(GRI Institute)
Continental European jurisdictions present contrasting fundamentals, characterised by low provision rates and distinct occupier profiles.
In France, student housing demand is dominated by domestic occupiers, who comprise roughly 80% of the market, alongside international mobility from North Africa and the Middle East.
Limited regional purchasing power constrains rental growth in secondary French cities, though institutional capital continues to enter the sector due to constrained opportunities in traditional office assets and tight margins in Build-to-Rent (BTR) residential platforms.
French domestic banks support the sector with low-cost debt financing, treating student assets as stable residential real estate.
Meanwhile, Italy represents a compelling growth market marked by an acute undersupply of student beds, with national provision rates lingering near 4%.
Demand is supported by an annual 14% growth rate in international student enrolments since 2019, driven by an expansion of English-taught university programmes from 314 to over 1,300. Out of 2 million annual enrolments, 800 thousand represent mobile domestic students, creating a broad addressable tenant base.
However, severe cost inflation has raised development expenses in major Italian cities to EUR 90 thousand per bed, with Furniture, Fixtures, and Equipment (FF&E) adding EUR 9 thousand to EUR 10 thousand per bed.
Capturing necessary rental yields requires granular, micro-location underwriting to target mobile domestic and international students enrolled at private institutions paying over EUR 10 thousand in annual tuition.
The financial attractiveness of Italian student housing is further enhanced by tax-efficient investment structures.
Utilising a Special Purpose Vehicle (SPV) managed by an Asset Management Company, known locally as a Società di Gestione del Risparmio (SGR), establishes a tax-transparent structure with 0% withholding tax on dividends and 0% capital gains tax, leaving operators responsible primarily for municipal property taxes of approximately 50 basis points.
Despite these advantages, investors must avoid over-relying on aggregate student-to-bed ratios, which frequently overestimate demand by ignoring non-mobile students living at home. In addition, secondary European cities face localised absorption risks if multiple schemes deliver simultaneously into small regional markets.
► Operational Execution
(GRI Institute)
Operational success across European markets depends heavily on adapting to regional leasing behaviours.
While UK and US schemes secure pre-lets six to nine months prior to the academic year, Continental European markets operate within a compressed two-month window between August and October.
This short timeframe requires proactive marketing strategies, including active digital branding, social media engagement on platforms like TikTok, and live video walkthroughs to establish credibility and reassure international students wary of online accommodation scams.
Spatial design standards have evolved from basic, loose-furnished rooms toward highly functional, fitted interiors.
Modern layouts incorporate hotel-style bed orientations, walk-around fitted wardrobes, and integrated bedside charging stations, which optimise small spaces while reducing long-term maintenance costs.
Layout innovation has also introduced hybrid formats such as studio clusters, where tenants enjoy private rooms with micro-kitchenettes containing a sink and microwave alongside shared lounge and dining spaces, balancing individual privacy with social community.
Operator differentiation is increasingly driven by thoughtful amenity curation and value-added operational services.
High-performing assets feature comprehensive wellness spaces, including dedicated cardio rooms, yoga studios, weights rooms equipped with dumbbells up to 40 kg, roof terraces, and private dining rooms.
Operational perks, such as providing one free laundry wash per week - costing operators GBP 0.50 to GBP 0.75 while saving tenants GBP 7.00 - and bi-weekly room cleaning, deliver tangible value that helps justify premium rental rates across competitive European markets.
► European PBSA Outlook
The European student housing sector is entering a refined phase where market-wide expansion is giving way to asset-level discrimination, shifting the core investment thesis from simple volume delivery to operational performance, brand equity, and design-led differentiation.Over the medium term, the UK market is positioned for a strong rebalancing and pricing recovery as regional ground-up development halts under replacement cost barriers, HMO stock continues its regulatory exit, and student demand concentrates into surviving high-quality assets.
At the same time, Continental European markets will reward capital that balances low provision opportunities against micro-location risks, short leasing windows, and local purchasing power constraints.
Ultimately, as first-generation properties face accelerating technical obsolescence, long-term resilience across Europe will belong to platforms that combine strong digital branding, tenant-centric amenities, and efficient spatial layouts to capture enduring occupier loyalty.
► Access the full Europe GRI 2026 - Summer Edition Spotlight report here
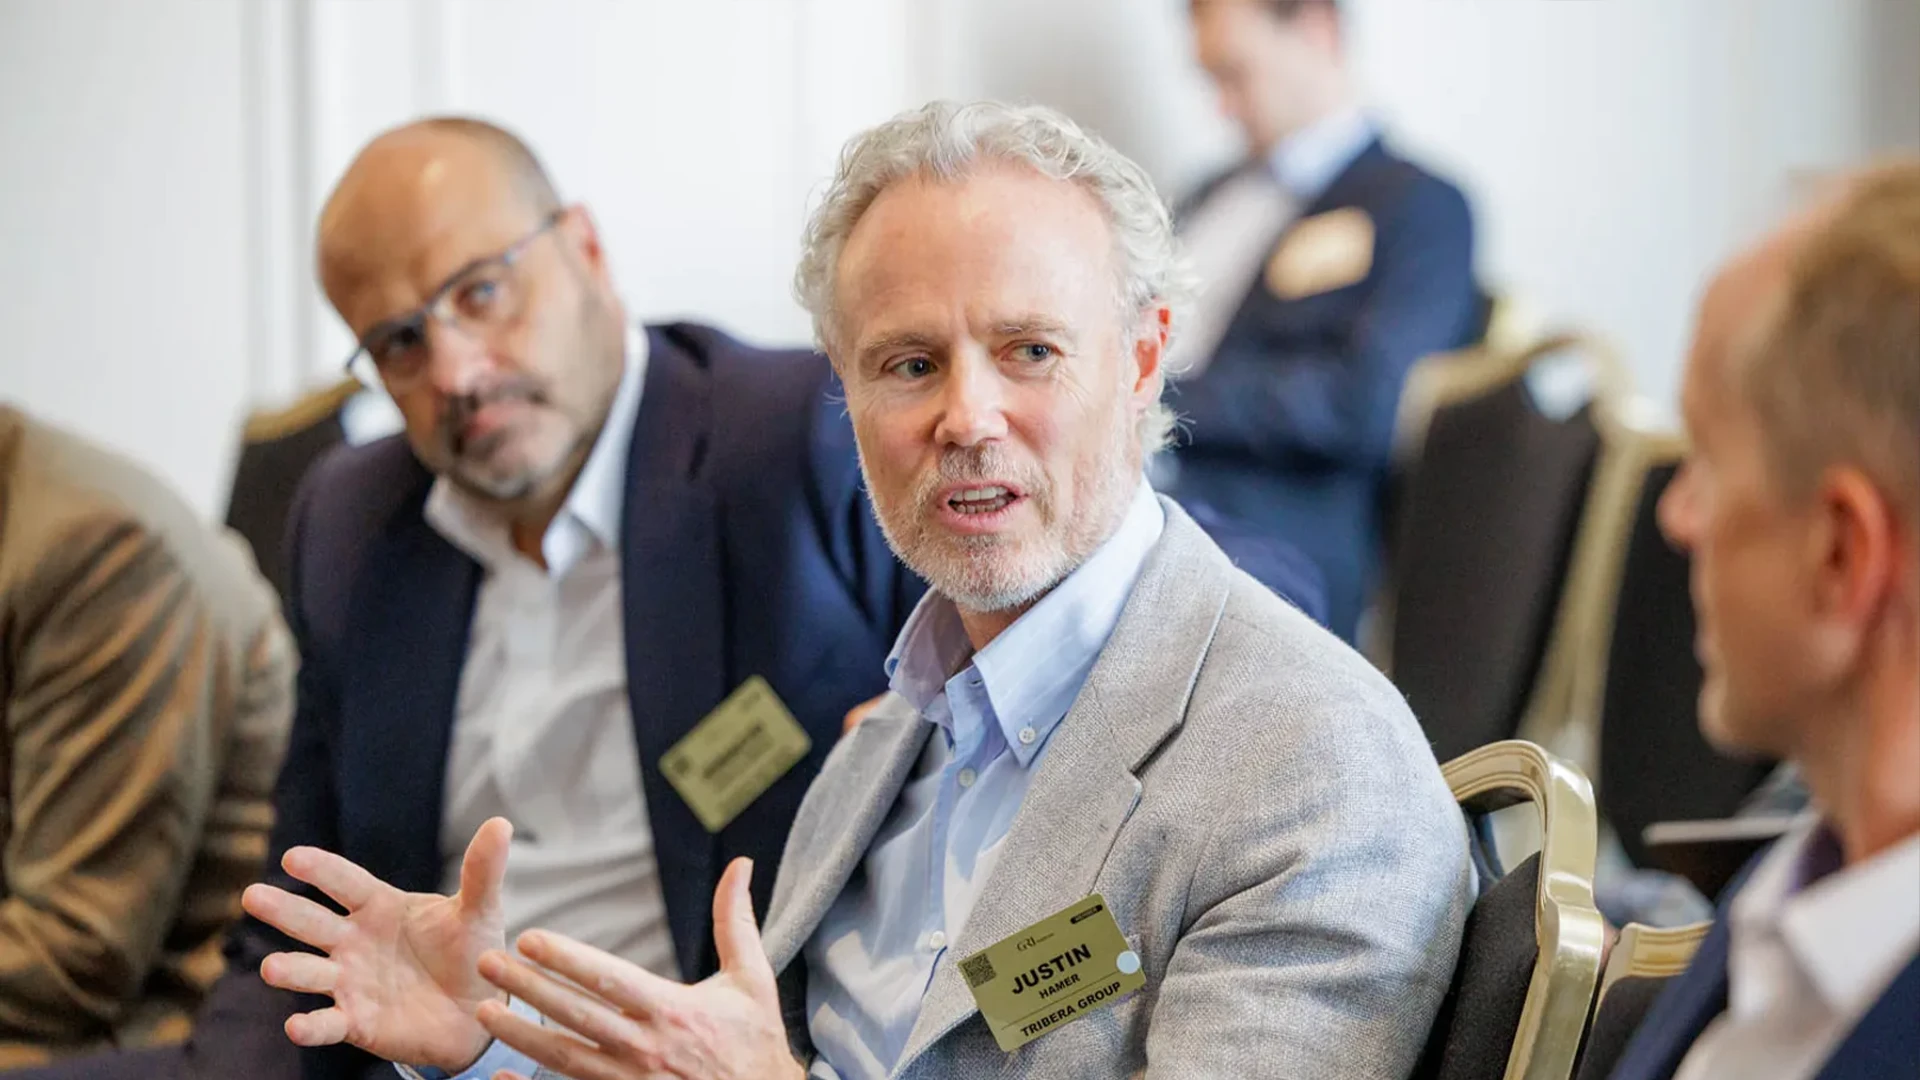
These insights were shared at the PBSA panel at Europe GRI 2026 - Summer Edition, moderated by Alexander Riches (Crosswind Capital), with panellists Daniel Harris (Fusion Group), Giulio Bentivoglio (KERVIS), Justin Hamer (Tribera Group), Luca Turco (Praemia REIM), and Matt Walker (Mapletree).